fincite x harvest logo

Product

Clients

About us

Knowledge Hub

Product

Clients

About us

Knowledge Hub

Product

Clients

About us

Knowledge Hub

Product

Clients

About us

Knowledge Hub

Onboarding

CIOS keynote image

Watch the Onboarding Tutorial

Product

Clients

About us

Knowledge Hub

Onboarding

CIOS keynote image

Watch the Onboarding Tutorial

Product

Clients

About us

Knowledge Hub

Onboarding

CIOS keynote image

Watch the Onboarding Tutorial

EUDI Wallet and eIDAS 2.0 for Wealth Managers and Banks

EUDI Wallet and eIDAS 2.0 for Wealth Managers and Banks

EUDI Wallet and eIDAS 2.0 for Wealth Managers and Banks

EUDI Wallet and eIDAS 2.0 for Wealth Managers and Banks

The EUDI Wallet is changing the foundation of digital identity for all financial institutions in the EU. Regulated banks and wealth management providers must accept the European Digital Identity Wallet for onboarding and customer authentication.

The Retirement Provision Reform Act creates a completely new product category. 16 million Riester contracts can be switched. fincite • cios prepares your institution for 01.01.2027.

Digital asset management with
fincite • cios. The all-in-one software
for advisors.

What is currently occupying banks and wealth managers

What is currently occupying banks and wealth managers

What is currently occupying banks and wealth managers

The deadlines have been set. Which platform can cover them is still an unanswered question for most institutions.

From 1 January 2027, financial institutions can offer the new retirement savings depot, and from that date, no more traditional Riester contracts can be concluded.


The retirement savings depot replaces the old Riester pension with a modern, capital market-based product category: ETFs, stocks, and active funds will be eligible for the first time. Around 16 million existing Riester contracts can voluntarily switch to the new retirement savings depot.


For institutions, this means: Whoever has a market-ready solution on 1 January 2027 secures access to a billion-euro market.

From 1 January 2027, financial institutions can offer the new retirement savings depot, and from that date, no more traditional Riester contracts can be concluded.


The Altersvorsorgedepot replaces the old Riester pension with a modern, capital market-based product category: ETFs, stocks, and active funds will be eligible for the first time. Around 16 million existing Riester contracts can voluntarily switch to the new retirement savings depot.


For institutions, this means: Whoever has a market-ready solution on 1 January 2027 secures access to a billion-euro market.

From 1 January 2027, financial institutions can offer the new retirement savings depot, and from that date, no more traditional Riester contracts can be concluded.


The retirement savings depot replaces the old Riester pension with a modern, capital market-based product category: ETFs, stocks, and active funds will be eligible for the first time. Around 16 million existing Riester contracts can voluntarily switch to the new retirement savings depot.


For institutions, this means: Whoever has a market-ready solution on 1 January 2027 secures access to a billion-euro market.

December 2027. The deadline is set, but whether their own onboarding system can accommodate a new authentication method remains an unanswered question for most institutions.

Three identification methods. From July 2027, the AMLR requires that all three recognised remote identification methods are supported: national eID systems, the EUDI Wallet and Qualified Trust Services. Anyone covering only one method will have a compliance gap for certain customer groups.

Cross-Border Onboarding. The onboarding of European customers from other EU countries is currently a document-intensive, additional effort per country. The EUDI Wallet solves this technically, provided the platform can integrate the method.

Every new regulation becomes a project. Monolithic onboarding systems cannot configure new authentication methods. Modular platforms with open APIs can.

The next generation of clients expects it. Next-gen clients from the Great Wealth Transfer judge the very first digital interaction. The EUDI wallet sets the standard for the onboarding experience that this generation expects.

The most important dates at a glance

The most important dates at a glance

The most important dates at a glance

From eIDAS 2.0 to the obligation to accept: these dates determine when which requirement takes effect and who it affects.

The retirement provision depot is no longer a standard depot.
Each of these requirements is a project in its own right. Together, they require a complete platform.

May 2024

eIDAS 2.0 enters into force. The legal framework applies with immediate effect.

All companies in the EU

24 December 2026

All EU member states provide at least one EUDI Wallet.

Member States

1 January 2027

Public bodies must accept the EUDI Wallet for identification purposes.

Authorities and public bodies

10 July 2027

The AMLR comes into effect. All three remote KYC methods must be supported.

Regulated financial institutions

24 December 2027

Medium-sized and large financial institutions must accept the EUDI Wallet.

Banks, insurance companies, payment service providers

What matters now

Three recognised methods in parallel: national eID systems, EUDI Wallet and Qualified Trust

Services. Anyone who covers only one path has a compliance gap for certain customer groups.

What the EUDI Wallet means for financial institutions

What the EUDI Wallet means for financial institutions

What the EUDI Wallet means for financial institutions

From cross-border onboarding to re-KYC: the EUDI wallet is transforming the core processes of regulated financial institutions.

A production-ready platform requires 6 to 9 months of implementation time.
With a market launch on January 1, 2027, this means those who waits until summer 2026 will go live in 2028 at the earliest.

From cross-border onboarding to re-KYC: the EUDI wallet is transforming the core processes of regulated financial institutions.

Cross-Border Onboarding

An EU citizen opens an account with a German private bank using their EUDI Wallet identity in minutes. No country-specific document workflow, no manual review.

EU-wide identity recognition

The customer's PID is cryptographically verified and legally recognised across all 27 EU member states. Customers identify themselves once and can use the same identity at multiple institutions EU-wide.

Seamless digital Re-KYC

With the EUDI wallet, existing customers transmit updated attributes in a cryptographically verified manner without having to go through another identification process. For institutions with large portfolios of existing customers, this often represents a stronger operational lever than onboarding.

Onboarding Efficiency

Cryptographically verified attributes reduce manual KYC checks and accelerate account opening. For digitally-savvy customer groups, this improves the onboarding experience.

Selective Disclosure and Data Protection

Instead of keeping a copy of the ID in the archive, the customer only transmits the queried attribute, which is cryptographically verified and documented in an audit-proof manner. Less data storage, lower audit effort, seamless proof without screenshot folders.

New competitive advantages

Institutions that are among the first to integrate the EUDI wallet position themselves as digital trust anchors for their customers. Those who wait accept the wallet as a verifier in an ecosystem that others have built.

How fincite • cios prepares financial institutions

Customer onboarding –
smart & secure!

Customer onboarding –
smart & secure!

CIOS Onboarding already integrates identity providers such as IDNow, WebID and Deutsche Post via open APIs using the same architectural logic. The implementation time for new authentication methods depends directly on the flexibility of the onboarding system.

CIOS Onboarding already integrates identity providers such as IDNow, WebID and Deutsche Post via open APIs using the same architectural logic. The implementation time for new authentication methods depends directly on the flexibility of the onboarding system.

Efficient onboarding with automated data collection and
legally compliant documents.

API-first architecture

New identification methods are integrated via existing open interfaces.

Identity integration today

End-to-end without system disruption

Proven in practice

API-first architecture

New identification methods are integrated via existing open interfaces.

Identity integration today

End-to-end without system disruption

Proven in practice

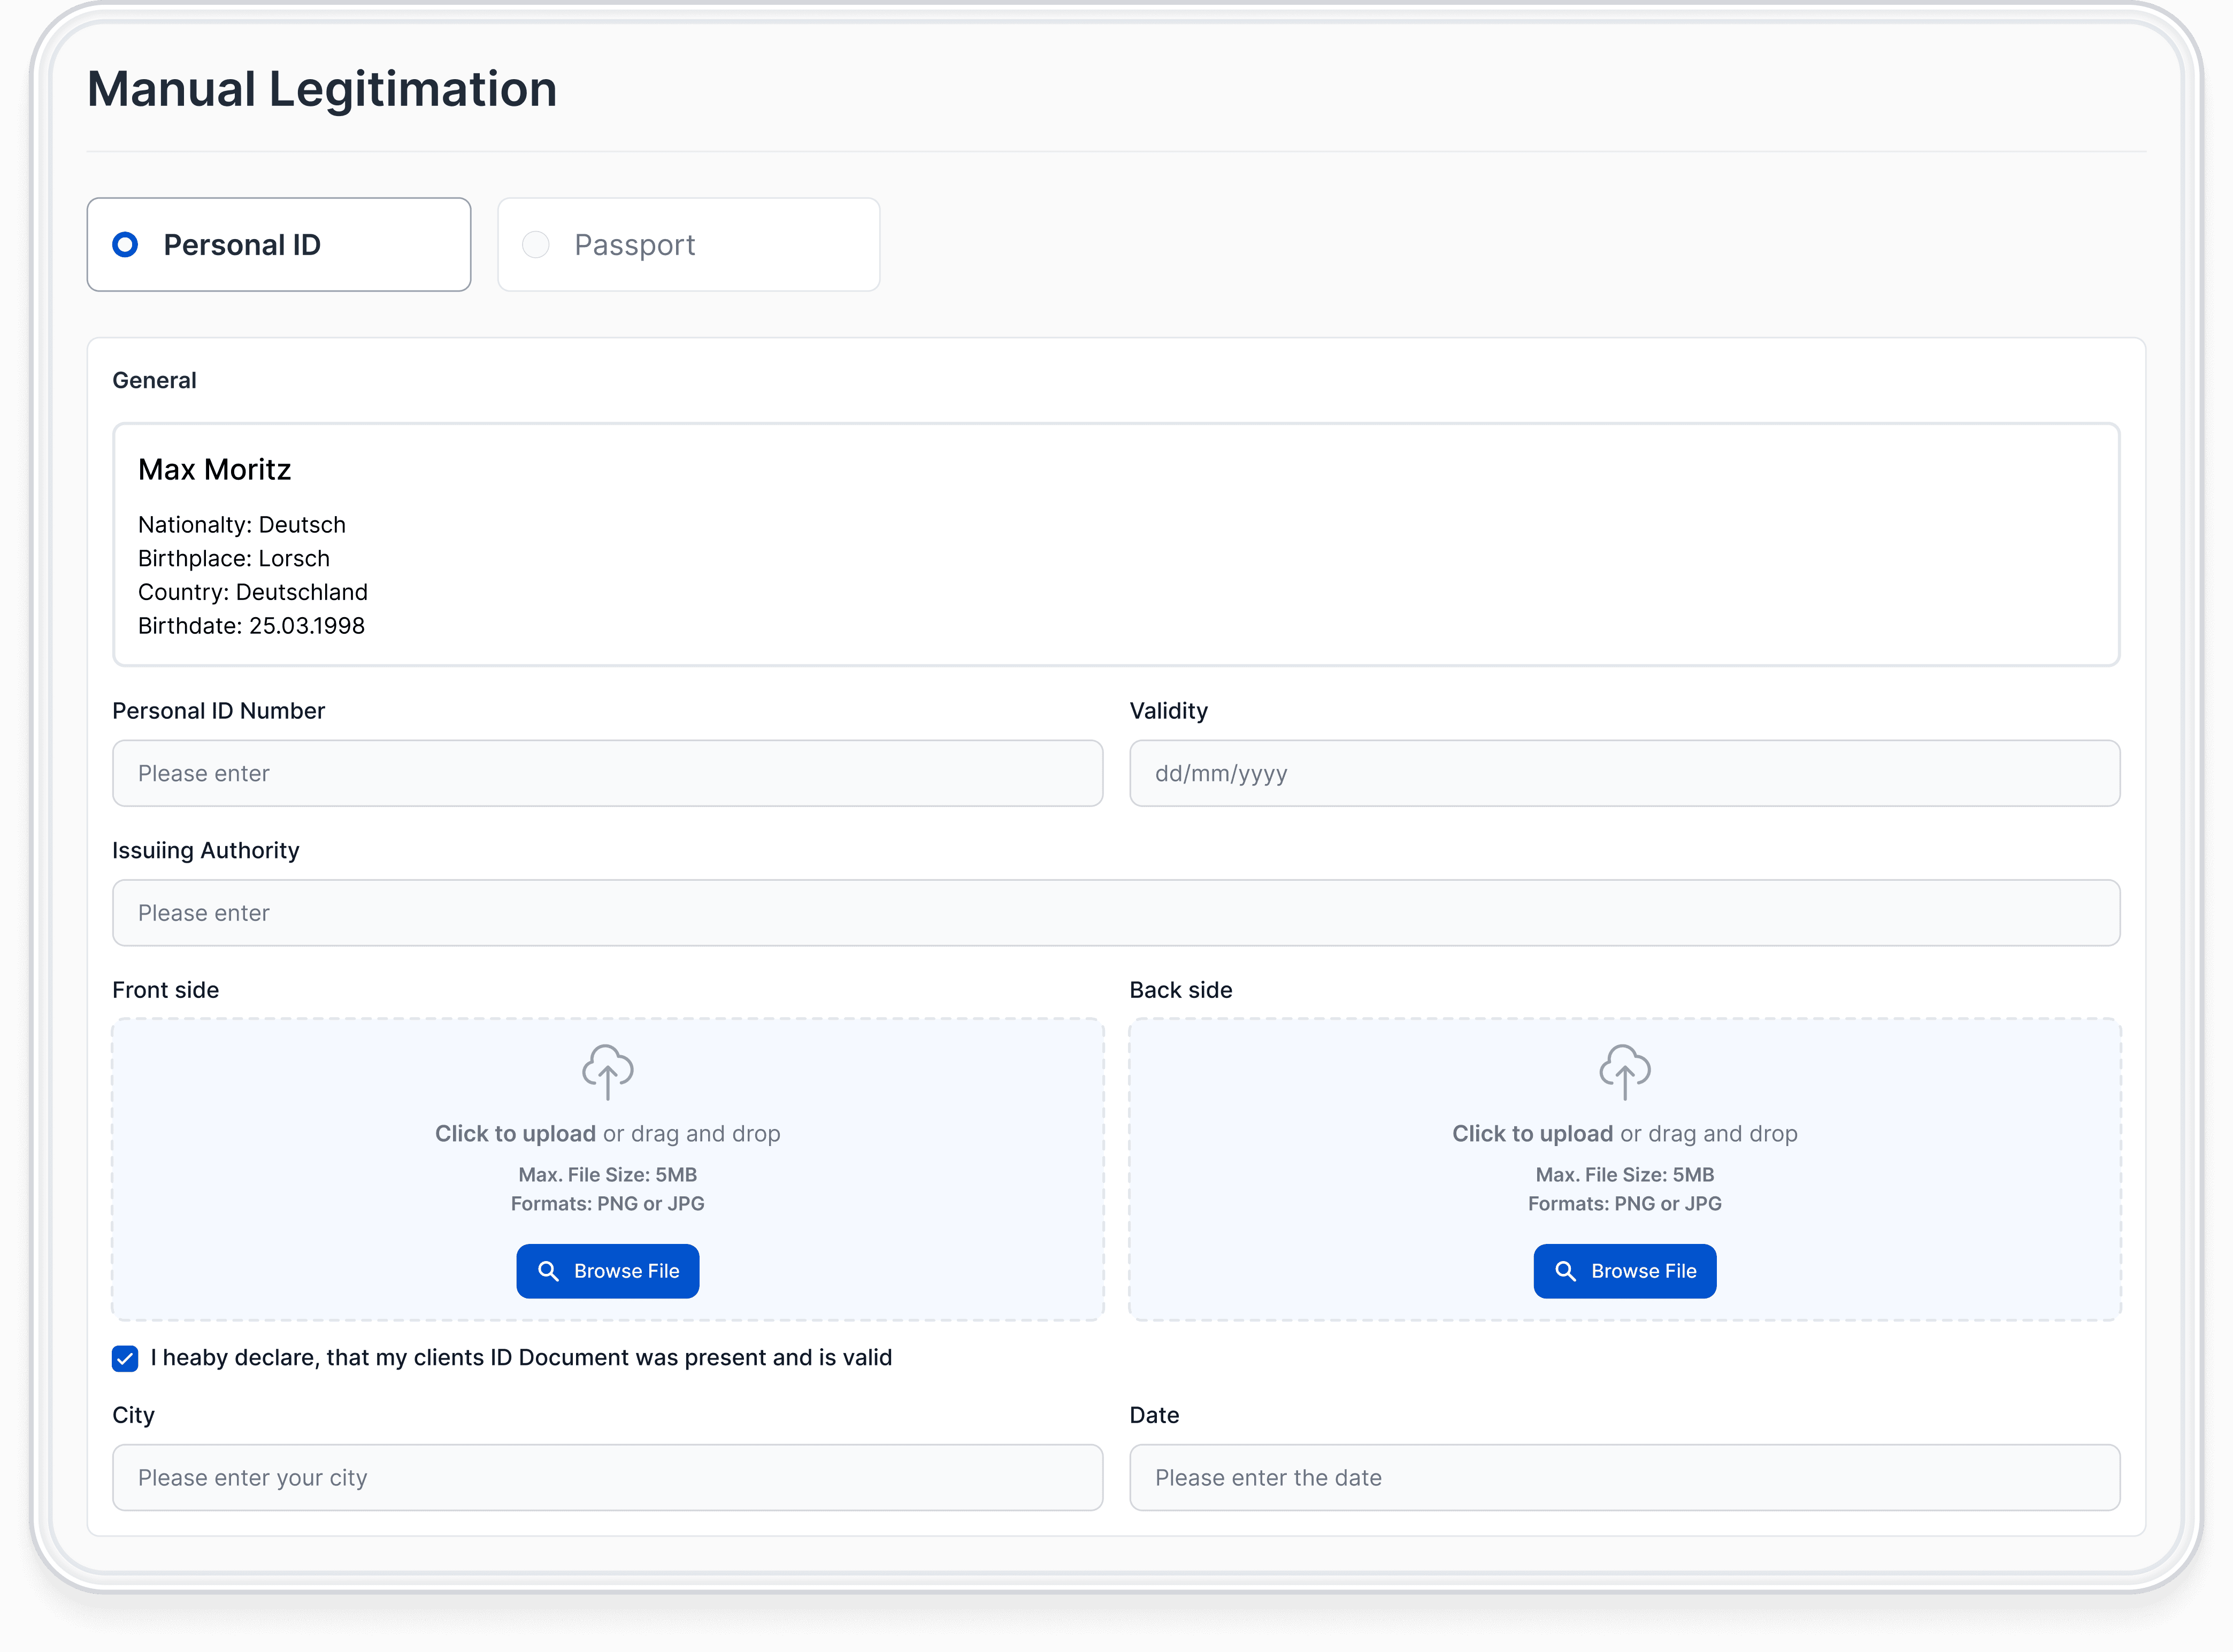
Close-up of the manual legitimization screen showing input fields for ID verification, document upload, and user details.

Frequently asked questions

Frequently Asked Questions

What is the EUDI Wallet?

The EUDI Wallet (European Digital Identity Wallet) is a digital identity solution provided by EU member states. Within it, citizens store verified identity attributes and use them to identify themselves with legal validity across the EU. For financial institutions, it will become an accepted method for onboarding and strong customer authentication starting from December 2027.

From when must banks accept the EUDI Wallet?

What does the AMLR require from July 2027?

What does the EUDI Wallet mean for cross-border onboarding?

What is fincite • cios?

Why does the platform architecture determine the effort involved?

What is the EUDI Wallet?

The EUDI Wallet (European Digital Identity Wallet) is a digital identity solution provided by EU member states. Within it, citizens store verified identity attributes and use them to identify themselves with legal validity across the EU. For financial institutions, it will become an accepted method for onboarding and strong customer authentication starting from December 2027.

From when must banks accept the EUDI Wallet?

Which features are available?

What does the EUDI Wallet mean for cross-border onboarding?

What is fincite • cios?

How does fincite • cios compare to other wealth management software?

What is the EUDI Wallet?

The EUDI Wallet (European Digital Identity Wallet) is a digital identity solution provided by EU member states. Within it, citizens store verified identity attributes and use them to identify themselves with legal validity across the EU. For financial institutions, it will become an accepted method for onboarding and strong customer authentication starting from December 2027.

From when must banks accept the EUDI Wallet?

Which features are available?

What does the EUDI Wallet mean for cross-border onboarding?

What is fincite • cios?

Why does the platform architecture determine the effort involved?

93%

Customer satisfaction

630k+

End customers

83%

Cost savings

9k+

Financial Advisor

93%

Customer satisfaction

630k+

End customers

83%

Cost savings

9k+

Financial Advisor

93%

Customer satisfaction

630k+

End customers

83%

Cost savings

9k+

Financial Advisor

93%

Customer satisfaction

630k+

End customers

83%

Cost savings

9k+

Financial Advisor

Start your project with us!

Start your project with us!